How to Buy a Business With Seller Financing: A Practical 2026 Guide
Could the seller help fund the business you want to buy? If you’re researching how to buy a business with seller financing, the seller may agree to finance part of the purchase through a note that you repay over time. This can help bridge a funding gap, but it doesn’t make an unsupported asking price or an unworkable payment schedule a sound deal.
It’s reasonable to feel uncertain about the terms, especially if the business’s records don’t clearly support its valuation or you’re weighing an SBA loan alongside a seller note. Treat seller financing as one part of a verified acquisition capital plan, not as a shortcut around careful analysis.
This guide explains how to move from an initial conversation with the seller to a financing structure that can work through closing. You’ll learn what to assess in the business’s financial records and cash flow, which repayment terms to discuss, and how a seller note may fit with SBA or other acquisition capital. Business valuation, M&A consulting, and capital planning can help connect the purchase price to the business’s performance and the funding required.
Key Takeaways
- Learn how to buy a business with seller financing by understanding how a seller note works and which repayment terms to discuss.
- Review financial records, customer concentration, contracts, liabilities, and operating trends before deciding whether the asking price is supportable.
- Estimate sustainable debt payments using normalized cash flow and the working capital the business needs to operate.
- Compare seller financing with SBA-backed financing, buyer cash, and working capital to see how each source affects repayment and deal flexibility.
- Use a clear offer structure and a step-by-step process to move from seller discussions through due diligence, documentation, and closing.
How seller financing works when you buy a business
Seller financing is credit the business seller extends to the buyer through a promissory note for part of the purchase price, repaid under agreed terms after ownership transfers. The seller, rather than a financial institution, becomes the creditor for that portion of the deal. The parties negotiate the note as part of the overall transaction. What is Seller Financing? offers a general overview of this arrangement across business and real estate transactions.
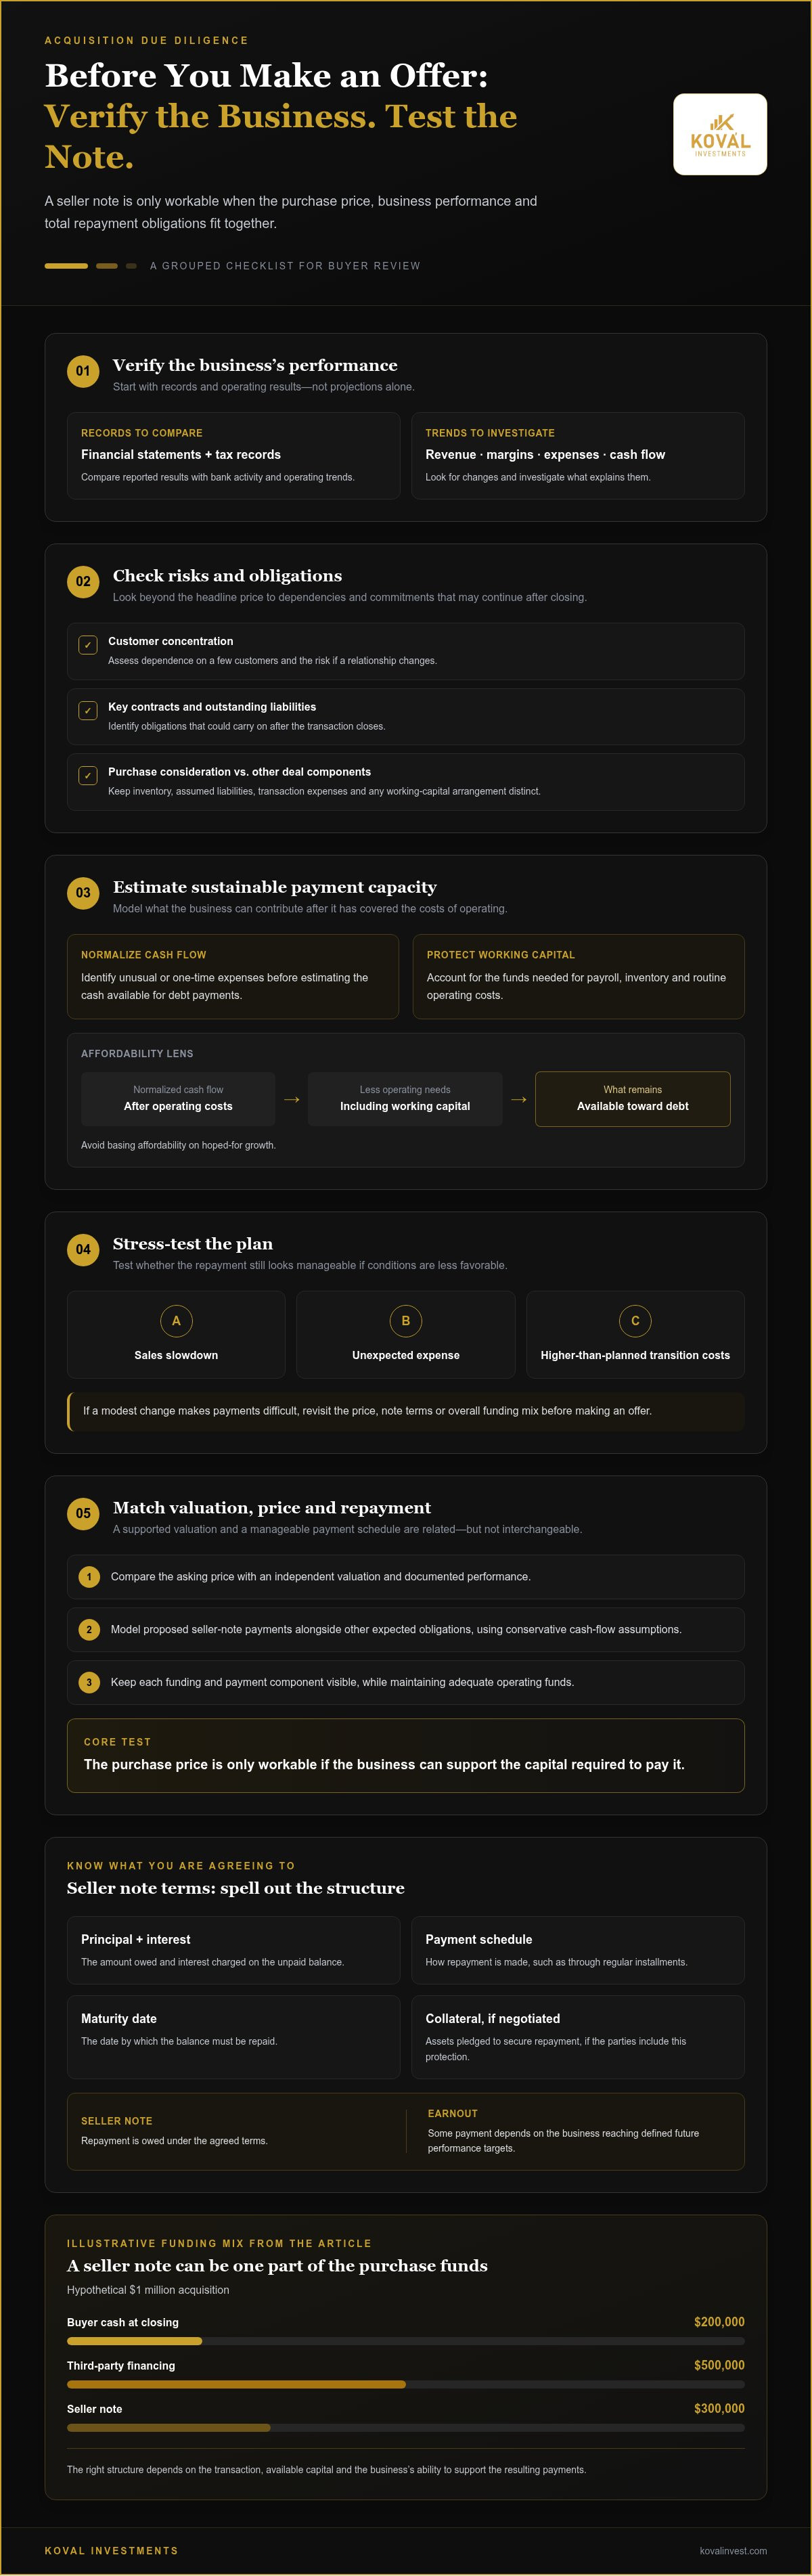
The note is only one source of purchase funds. A buyer might contribute cash at closing, obtain financing from a bank or SBA-backed lender, and use a seller note to cover another part of the agreed consideration. Each source comes with its own repayment obligations. For example, in a hypothetical $1 million acquisition, a buyer might bring $200,000 in cash, arrange $500,000 in third-party financing, and negotiate a $300,000 seller note. The right structure depends on the transaction, available capital, and the business’s ability to support the resulting payments.
For anyone learning how to buy a business with seller financing, the central question isn’t just whether the seller will carry a note. It’s whether the proposed terms and total debt fit the business’s cash flow after the buyer takes over.
What a seller note usually covers
A seller note sets out the principal owed and the interest charged on the unpaid balance. It also specifies the payment schedule, such as regular installments, and the maturity date by which the balance must be repaid. If the parties negotiate this protection, the agreement may include collateral, meaning assets pledged to secure repayment. Terms vary by transaction, so model the actual proposed terms rather than assume a standard structure.
A seller note is different from an earnout. With a note, the buyer owes repayment under the agreed terms. An earnout generally makes some payment contingent on the business reaching defined future performance targets. The distinction matters: a fixed payment affects cash flow even if results soften, while an earnout payment depends on the agreed measurements and conditions.
Why buyers and sellers may consider seller financing
A seller note can bridge the gap between the buyer’s available cash and the purchase consideration the parties have agreed on. It may also help move a transaction forward when both parties see value in the business but need a different funding structure. For the seller, receiving payments over time preserves a financial interest after the transfer and may signal confidence in the business’s prospects. That alignment can support a constructive transition, but it doesn’t remove the buyer’s obligation to pay.
Flexibility has trade-offs. The buyer must assess whether payments remain manageable alongside operating costs and any third-party debt. The seller takes the risk that the buyer may not repay as promised. A workable arrangement depends on clear terms, realistic cash-flow assumptions, and a purchase price supported by the business’s financial performance, not simply on both parties’ willingness to sign a note.
How to assess the business and seller-financing terms before making an offer
To understand how to buy a business with seller financing, assess the business and the proposed repayment together. Start with records that show how the company has performed, not just the seller’s projections. Review financial statements and tax records, then compare reported results with bank activity and operating trends. Look for changes in revenue, margins, expenses, and cash flow, and investigate what explains them.
Due diligence should also cover customer concentration, key contracts, outstanding liabilities, and obligations that could continue after closing. A company that depends heavily on a few customers, for example, may face added risk if one relationship changes. Wall Street Prep’s Understanding Seller Financing and Seller Notes provides additional context on how seller notes fit into business acquisitions.
- Identify unusual or one-time expenses before estimating normalized cash flow.
- Account for working capital needed to cover payroll, inventory, and routine operating costs.
- Separate the agreed purchase consideration from inventory, assumed liabilities, transaction expenses, and any working-capital arrangement.
Use normalized cash flow to estimate what the business can reasonably contribute toward debt payments after operating costs and working-capital needs. Don’t base affordability on hoped-for growth. Stress-test the plan against a sales slowdown, an unexpected expense, or higher-than-planned transition costs. If a modest change makes payments difficult, revisit the price, note terms, or overall funding mix before making an offer.
Test whether the purchase price and repayment fit
Compare the asking price with an independent valuation and documented performance. Then model the proposed seller-note payments alongside other expected obligations, using conservative cash-flow assumptions. Keep each component visible so you can see whether the business can cover payments while maintaining adequate operating funds. Valuation and repayment capacity belong in the same analysis: a price is only workable if the business can support the capital required to pay it.
A valuation may support the asking price while the business’s cash flow cannot comfortably carry the proposed repayment schedule. Or the payment may appear manageable only because the model assumes immediate growth. In either case, the gap is useful negotiation information, not a reason to overlook the numbers.
Identify seller-note terms that change the risk
Review the interest rate, payment frequency, amortization schedule, maturity date, and any grace period. Check whether the note has a balloon payment, which requires a larger final payment, and understand the consequences of missed payments. Clarify whether collateral or a personal guarantee is proposed and whether the seller note is subordinated to third-party financing. These provisions can materially affect cash flow and the buyer’s exposure.
Before signing, have qualified legal and financial professionals review the written terms, including default provisions and how the note interacts with other financing. Business valuation and M&A guidance can help connect documented performance to the proposed price and repayment plan. For support assessing that relationship, professional business valuation services can inform acquisition decisions.
Seller financing vs. SBA and other acquisition funding
Most acquisition plans combine sources with different costs, approval steps, repayment obligations, and effects on day-to-day cash. A seller note may cover a negotiated portion of the purchase, while an SBA-backed loan or buyer cash funds other parts. Working capital serves a different purpose: it helps the business meet operating needs after closing. For buyers considering how to buy a business with seller financing, comparing the whole structure is more useful than focusing on one rate or funding source in isolation.
The comparison below is a starting point. Actual terms depend on the transaction, the business’s records, the buyer’s circumstances, and, for external financing, lender underwriting.
| Funding source | Source and repayment | Timing and flexibility | Diligence focus |
|---|---|---|---|
| Seller note | Seller finances an agreed portion; buyer repays under the note’s terms. | Negotiated directly within the deal, but lender approval or lien priority may affect structure. | Assess seller-note terms, cash-flow fit, collateral, and any subordination requirements. |
| SBA-backed financing | A participating lender provides financing, with an SBA guaranty subject to program rules; the buyer makes scheduled repayments. | Application and underwriting take time; permitted terms depend on lender and program requirements. | Expect review of the buyer, transaction, business performance, and supporting records. |
| Buyer cash | Funds come from the buyer and don’t create a loan payment. | Available at closing, but using too much can reduce the buyer’s post-close reserve. | Plan for both the required contribution and liquidity after the purchase. |
| Working capital | Funds support operating needs; repayment depends on the specific financing arrangement. | Can help cover ongoing needs, though access and structure vary. | Estimate cash needed for payroll, inventory, receivables, and routine expenses. |
When a seller note may complement other capital
A seller note can fill a negotiated gap between buyer cash and third-party financing, but combining sources requires coordination. A lender may need to approve the seller note’s payment terms, and lien priority determines which creditor has a claim on pledged assets first. Subordination may also affect whether seller payments can be made while another loan is outstanding. Buyers comparing structures can review SBA loan assistance as part of acquisition planning.
Compare the full funding plan, not just the headline rate
Compare scheduled payments alongside fees, covenants, collateral, and restrictions on future borrowing. Then check how much cash remains for operations after closing. Working capital supports payroll, inventory, and other business needs; it shouldn’t be treated as interchangeable with money allocated to the purchase price. Preserving operating liquidity may make a plan more resilient than using every available dollar at closing. Working capital for business acquisition can help frame that distinction.
Build a side-by-side funding model showing expected proceeds, payment timing, repayment obligations, and remaining cash. This makes trade-offs visible before you commit and helps align the seller note with lender requirements and the business’s operating needs.
How to negotiate and close a seller-financed business purchase
A sound negotiation turns the valuation and financing analysis into clear, conditional terms. If you’re learning how to buy a business with seller financing, keep the purchase price, cash due at closing, seller note, and any outside financing distinct in your offer. This makes the capital structure easier for both parties to evaluate and leaves room to respond to due diligence findings.
- Open the conversation. Discuss the seller’s goals, the business handover, and whether the seller is open to carrying a note. Treat early discussions as exploratory, not as a final commitment.
- Develop a supported offer. Use valuation findings and cash-flow analysis to frame the price and proposed note size. State cash at closing, seller-financed amount, and any third-party funding separately.
- Set conditions and terms. Outline key conditions, such as satisfactory due diligence and any required lender review. Identify the proposed down payment, interest rate, repayment term, payment timing, collateral, and default provisions for negotiation.
- Complete due diligence. Verify financial and operating records, customers, employees, contracts, and liabilities. Adjust or withdraw the offer if material facts differ from what supported the initial proposal.
- Finalize documents and close. Coordinate the purchase agreement, promissory note, any security documents, financing conditions, closing funds, and transition arrangements before ownership transfers.
Build a credible offer and negotiate practical terms
A credible offer explains how its price and seller-note amount relate to the business’s documented performance and sustainable cash flow. Lay out the purchase price, cash paid at closing, note principal, and conditions as separate items rather than presenting one headline figure. Negotiate the rate, term, payment schedule, collateral, and default provisions directly and transparently. Discuss transition support and access to the seller’s operational knowledge separately, with clear expectations about scope and timing.
Keep financing assumptions conditional until due diligence is complete and any lender has reviewed the proposed structure. This helps both sides avoid treating preliminary terms as settled when business records or financing requirements may change the plan.
Coordinate diligence, documents, and closing
Before signing, reconcile the final terms across the purchase agreement, promissory note, and security documents. Have transaction counsel review the definitive agreements and security documents; a mismatch can create uncertainty about payment obligations or remedies. Coordinate lender requirements with the seller-note terms so the closing structure works as a whole.
Confirm the closing funds, transfer responsibilities, and post-close working-capital plan before ownership changes hands. Document who will handle key introductions, training, and outstanding operational matters during the transition. M&A consulting and valuation can help organize the commercial and financial decisions behind an offer. Discuss acquisition planning and valuation support to bring those pieces into alignment.
Build a workable acquisition plan with valuation and capital support
A seller note is one component of an acquisition, not a substitute for a plan that connects the business’s value, operating cash flow, and available capital. The practical sequence is to validate the business, model the proposed note, compare funding paths, and negotiate an offer that reflects what you’ve learned. This keeps the purchase decision grounded in evidence while leaving room to adjust as due diligence progresses.
For buyers researching how to buy a business with seller financing, an integrated plan makes the numbers easier to explain to the seller and potential financing partners. It can also surface gaps early, before an initial proposal becomes a difficult commitment to unwind.
- Validate the target. Organize the available financial and operating information, and identify questions that could affect value, cash flow, or the transition.
- Model the seller note. Test proposed payments against realistic cash flow and the liquidity the business will need after the acquisition.
- Compare capital sources. Consider buyer funds, a seller note, SBA-backed financing, and working capital as distinct parts of the plan. Treat outside financing as subject to its own review and underwriting.
- Negotiate with evidence. Use the updated valuation and funding model to explain the proposed price, cash at closing, seller note, and key conditions.
Bring valuation and financing decisions into one plan
A valuation helps frame what the business may be worth; cash-flow analysis tests what the buyer can afford to pay and repay. Consider both alongside the seller-note terms and post-close liquidity. If due diligence uncovers a customer change, an unrecorded obligation, or a different working-capital need, update the assumptions rather than relying on the first version of the model. A clear plan links each proposed funding amount to a defined use and a supportable repayment source.
This combined view can also strengthen the negotiation. Instead of presenting a number without context, the buyer can explain how the proposed structure relates to documented performance, available cash, and the capital required to operate after closing. Professional business valuation and M&A consulting can help organize these considerations into a more informed acquisition decision.
Prepare for the next acquisition-planning conversation
Before discussing the structure with a seller or financing partner, assemble a concise working file. Include information about the target, the financial records reviewed, key due diligence questions, an initial valuation view, proposed seller-note terms, and assumptions for other funding sources. Note what remains unverified. This preparation keeps the conversation focused on material issues and makes it easier to revise the plan as new information comes in.
- Separate confirmed facts from estimates and open due diligence items.
- Show how the proposed note and other capital fit into the total funding plan.
- Track expected post-close cash needs so purchase funding doesn’t obscure operating liquidity.
Koval Investments provides business valuations, M&A consulting, and capital procurement support to help buyers assess value and consider acquisition funding paths. Capital procurement can help evaluate potential sources, but it doesn’t guarantee approval or specific terms. Explore Koval Investments’ business advisory and capital support to discuss an acquisition plan shaped around the target, proposed terms, and funding assumptions.
Move from a proposed deal to a confident next step
Turn your current assumptions into a decision you can explain and stand behind. If you’re working out how to buy a business with seller financing, organize the facts you have, note what still needs verification, and identify the terms that would make the acquisition workable. A clear plan gives you a stronger basis for deciding whether to proceed, revise the offer, or step away.
You don’t have to assess the business and its capital structure in isolation. Koval Investments’ business valuation and strategic advisory services can inform your assessment, while M&A consulting and capital procurement support can help you consider potential funding paths. Financing remains subject to the relevant terms and review, but a well-grounded plan can help you approach the process with greater clarity.
Discuss a business valuation and acquisition capital plan with Koval Investments. With analysis behind your next move, you can pursue an acquisition that fits both your goals and the business’s realities.
Frequently Asked Questions
Can you buy a business with no money down using seller financing?
Possibly, if the seller agrees to finance the full purchase consideration, but that doesn’t mean you can complete the acquisition without cash. Buyers researching how to buy a business with seller financing should also plan for closing expenses, operating cash, and any transaction-specific requirements. A business may need funds immediately after closing for payroll or inventory, for example. A no-down-payment structure can still leave the buyer with significant financial responsibilities.
How much of a business purchase can the seller finance?
There’s no universal share that a seller will finance. The amount depends on the seller’s willingness to accept payments over time, the business’s performance, the buyer’s proposed terms, and any conditions imposed by third-party financing. A seller may be open to carrying a modest portion but not most of the price. Discuss the amount alongside the buyer’s other funds and the business’s ability to support scheduled repayments.
Does seller financing require a down payment?
Not always. Down-payment expectations vary with the transaction and the overall financing structure. A buyer contribution is separate from the seller note: it’s the amount the buyer brings toward the purchase rather than borrows from the seller. A seller might agree to a note only if the buyer contributes cash at closing, while another deal may use a different mix. Make sure the offer states each source distinctly.
Can seller financing be combined with an SBA loan?
It may be possible, depending on current SBA program rules, lender underwriting, lien position, and how the transaction is structured. A lender may review the seller note’s repayment terms and how it interacts with other debt before determining whether the arrangement works. Requirements can vary by deal and may change, so verify current rules with the lender handling the transaction before relying on a seller note as part of the funding plan.
What happens if a buyer cannot make seller-financing payments?
The outcome depends on the signed documents. They may specify when a missed payment becomes a default, whether the buyer has time to cure it, and what rights the seller has regarding collateral or enforcement. Before closing, understand how the agreement treats late payments, notice, and remedies, including whether other financing is affected. Have transaction counsel review those provisions so you understand the consequences before accepting the repayment obligation.
Is seller financing safer than a bank loan for buying a business?
Neither is automatically safer. Compare the payment schedule, collateral, default rights, and conditions attached to each source. A seller note may have terms negotiated for the transaction, while a bank loan follows the lender’s underwriting and agreement. The better fit depends on the business’s cash flow and the buyer’s full capital plan. Consider how the obligations work together if revenue falls short of projections or expenses rise.
What documents are used for seller financing a business purchase?
Common documents include the business purchase agreement and a promissory note describing the repayment obligation. Depending on the deal, the parties may also use security documents covering collateral and other agreements that coordinate the seller note with outside financing. The purchase agreement and note should align on key terms, including the amount financed and closing conditions. Transaction counsel should review the definitive agreements and related documents before signing.