Creative Real Estate Funding Strategies: Compare Your Options in 2026
The financing that gets a deal closed isn’t always the financing that best supports the investment. A loan may cover the purchase but leave renovation costs unresolved, or provide quick access to capital with repayment terms that don’t fit your exit timeline. Comparing creative real estate funding strategies means looking beyond the amount available to the property, the full capital required, and how you’ll repay or refinance.
Conventional financing may not fit every property, timeline, or investment structure. Alternatives can differ in cost, collateral, repayment obligations, and ownership arrangements, so compare those commitments before choosing a path. This guide reviews options for acquisitions, renovations, and long-term ownership, with a focus on deal fit, capital needs, risks, and exit plans. It also covers practical questions and documents to prepare before speaking with capital providers. Koval Investments facilitates access to real estate investment funding. Eligibility and suitability depend on the borrower, property, intended use of funds, and provider criteria.
Key Takeaways
- Match a funding structure to the property, purpose, and planned exit rather than choosing by speed or headline terms alone.
- Compare creative real estate funding strategies using consistent criteria, including repayment source, collateral, control, and total obligations.
- Separate purchase funds, renovation capital, reserves, and carrying costs to see how much capital the deal actually requires.
- Review written terms for fees, payment timing, personal guarantees, ownership dilution, and default remedies before committing.
- Prepare deal details and funding requirements before speaking with capital providers. Suitability depends on the borrower, property, purpose, and provider criteria.
What Are Creative Real Estate Funding Strategies, and When Do They Fit?
Creative real estate funding strategies are deal-specific ways to finance an investment property beyond a conventional investment-property mortgage. They may change who provides the capital, when funds become available, what secures the financing, how repayment works, or whether another party receives an ownership interest. Creative financing is a broad term, so assess each option by its written terms rather than its label.
Alternative financing still involves review and financial obligations. A capital provider may assess the borrower, property, project, and repayment plan. Before committing, clarify the amount and timing of funds, repayment terms, collateral, and what happens if the project or exit takes longer than expected.
The right fit depends on the asset and its place in your investment plan. A property that needs substantial work may require renovation capital that a purchase mortgage doesn’t cover. A short-term need before a sale or refinance differs from financing intended to support long-term ownership. Available equity, reserves, borrower profile, and closing timeline can also narrow the practical choices.
When Does Creative Financing Make Sense for a Property Deal?
It may be worth comparing alternatives when a property’s condition complicates standard financing, the transaction timeline is tight, or the borrower’s profile doesn’t align with a lender’s conventional requirements. But a funding mismatch is different from weak deal economics. If projected income or sale proceeds can’t reasonably cover repayment and other costs, a more flexible structure won’t fix the shortfall. Flexibility doesn’t establish affordability or investment viability.
Which Deal Details Should You Define Before Comparing Options?
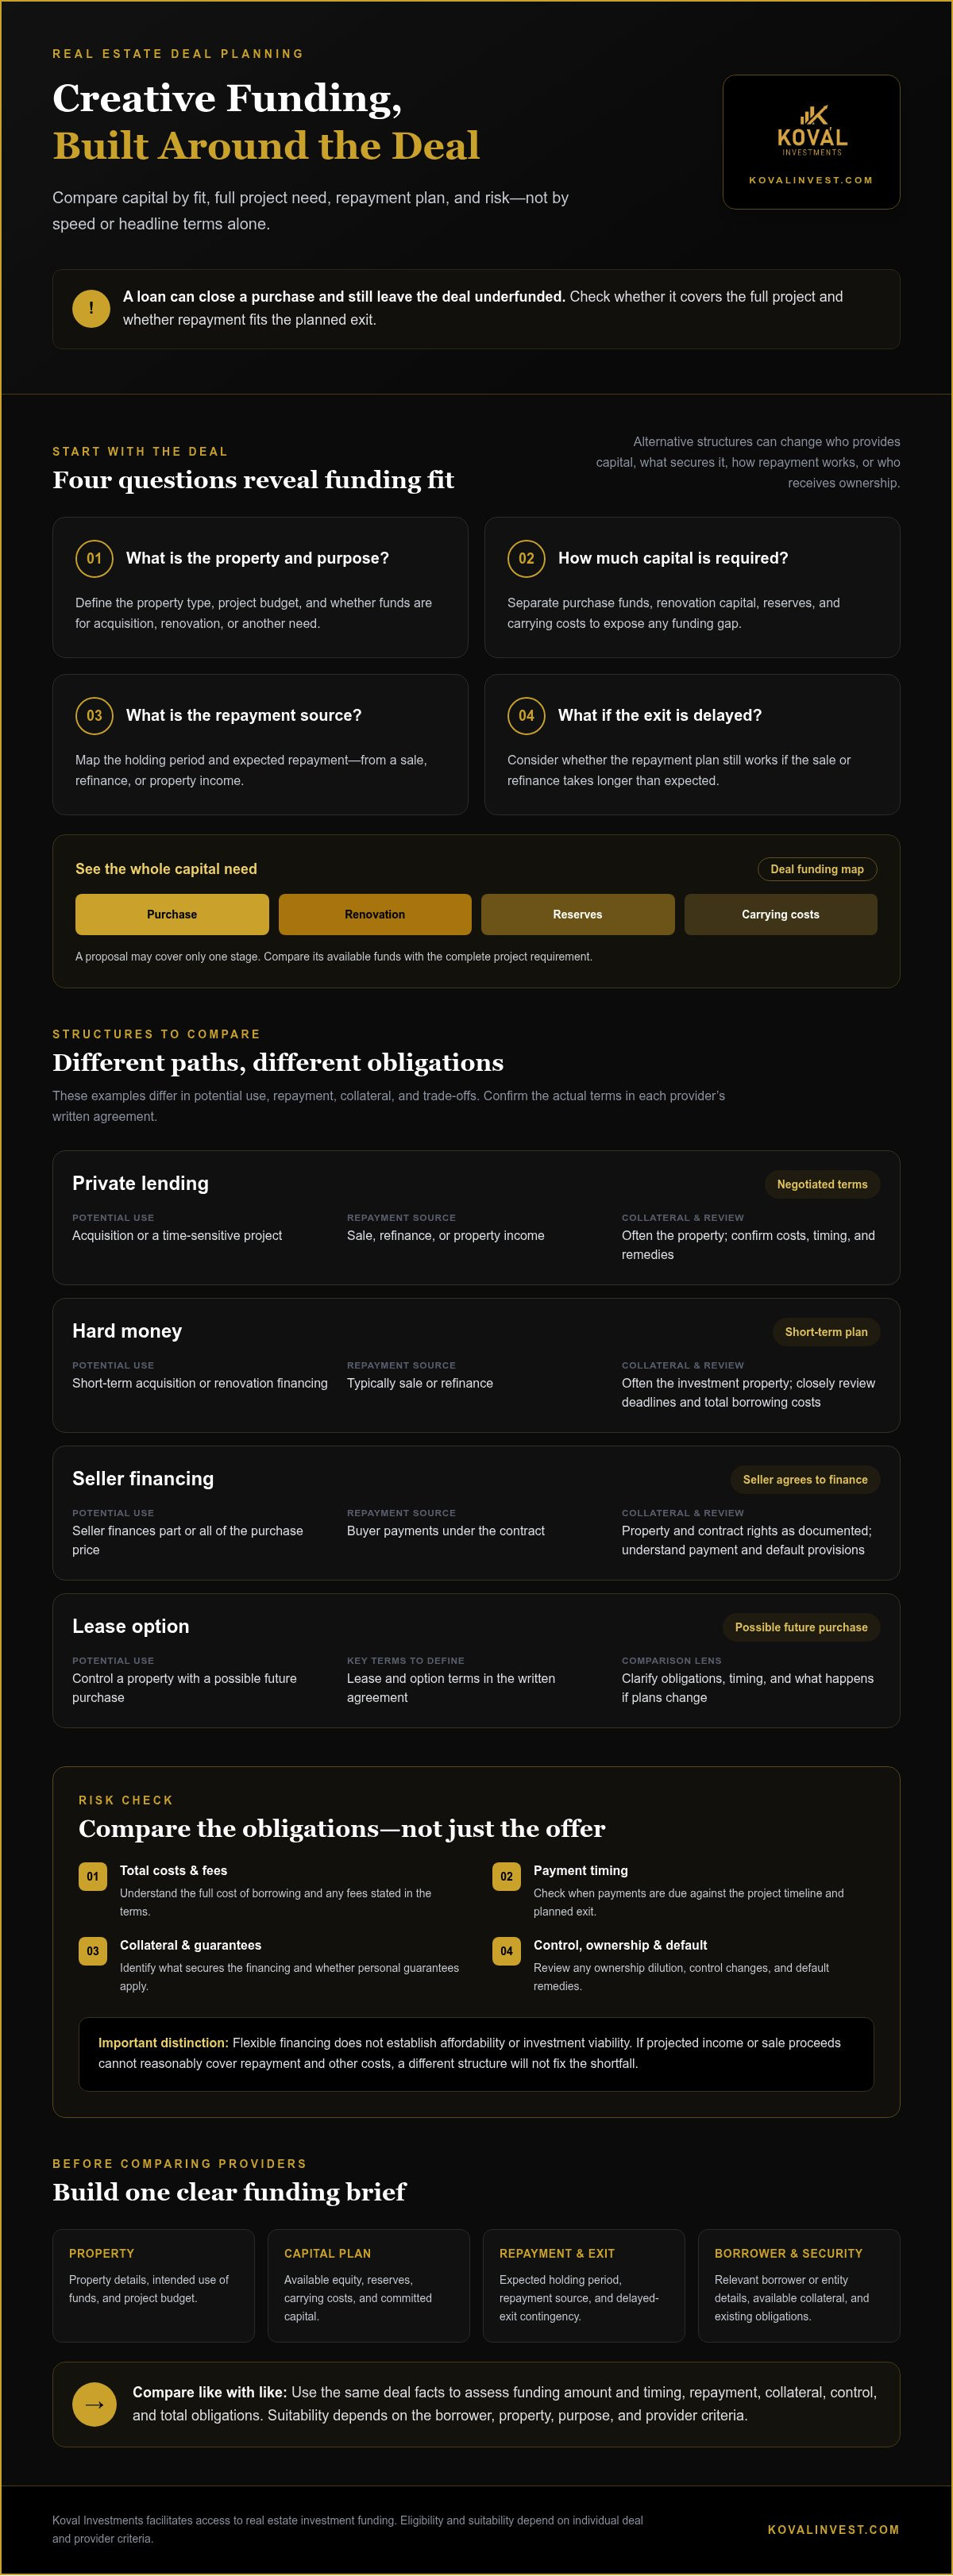
Start with a clear deal summary so providers can assess the same facts. Identify the property and intended use of funds, then map the project from acquisition through repayment. Specify the expected holding period and planned exit, such as a sale, refinance, or continued ownership. Defining the funding need and repayment source upfront makes comparisons more useful.
- Property and purpose: Property type, purchase or project budget, and whether funds will cover acquisition, renovation, or another need.
- Capital plan: Available equity, reserves, estimated carrying costs, and any other capital already committed.
- Repayment and exit: Expected holding period, source of repayment, and a contingency if the planned exit is delayed.
- Borrower and security: Relevant borrower or entity details, available collateral, and existing obligations tied to the property or other assets.
Separate purchase funds from renovation costs, reserves, and carrying costs. This shows whether a proposal covers the full project or only one stage. With those details in hand, you can compare structures against the deal’s needs and identify funding gaps before accepting terms.
Eight Creative Real Estate Funding Strategies to Compare
These creative real estate funding strategies differ in more than cost. Compare how each provides capital, what secures it, how repayment works, and whether you may give up control or ownership. Use the table as a starting point, then confirm the specific written terms with each provider.
| Structure | Potential use | Repayment source | Collateral | Principal trade-off |
|---|---|---|---|---|
| Private lending | Acquisition or a time-sensitive project | Sale, refinance, or property income | Often the property; confirm the agreement | Terms are negotiated, so verify costs, timing, and remedies directly with the provider. |
| Hard money | Short-term acquisition or renovation financing | Typically sale or refinance | Often the investment property | May suit a defined short-term plan, but payment deadlines and total borrowing costs need close review. |
| Seller financing | Purchase when the seller agrees to finance part or all of the price | Buyer payments under the contract | Property and contract rights, as documented | Negotiable terms can help structure a purchase, but both parties must understand payment and default provisions. Owner financing offers a useful overview. |
| Lease option | Control a property with a possible future purchase | Rent during the lease; purchase funds if the option is exercised | Contract rights rather than an immediate purchase loan | The option may expire unused; distinguish it from a lease-purchase, which commits the parties to a purchase. |
| Equity partnership | Acquisition or project needing another investor’s capital | Agreed distributions or sale proceeds | Ownership interest in the venture | No standard loan repayment schedule, but ownership, profit, and control are shared. |
| Real estate crowdfunding | Participation in a pooled or specific property investment | Depends on the investment structure | May be an investment interest, not direct property collateral | Platform terms, investor eligibility, liquidity, and compliance requirements vary. Verify them before investing. |
| HELOC or other credit line | Flexible access to acquisition or renovation capital | Borrower repayment, potentially supported by project proceeds | Depends on the line; a HELOC may put the borrower’s home at risk | Assess changing payments, repayment capacity, and collateral exposure before drawing funds. |
| Subject-to arrangement | Purchase where existing financing remains in place | Buyer makes payments on the existing loan | Property and existing loan terms | Transfer may trigger a due-on-sale clause. Wraparound versions add complexity; obtain qualified legal review. |
Match the Structure to the Deal Stage
Private lending and hard money may be options for time-sensitive purchases or renovation projects, but compare the actual terms and exit deadlines. Seller financing depends on the seller’s agreement and contract details. A lease option may give a buyer time to decide about purchasing, but it doesn’t guarantee the buyer can secure funds later. Subject-to and wraparound arrangements require careful review of existing loan terms and qualified legal advice.
Check Eligibility and Exposure Before Committing
Equity partnerships exchange some ownership and control for capital, while credit lines create repayment obligations and may expose other assets. Cross-collateralization can secure a loan with multiple properties, increasing the consequences of default. Self-directed IRA funds and business-purpose loans also have purpose-specific eligibility and use requirements. Verify current rules, provider criteria, and written terms. Investors comparing capital options may also review Koval Investments’ real estate investment funding. Suitability depends on the borrower, property, and funding purpose.
How to Compare Creative Funding Strategies Without Overlooking Risk
A funding offer can seem manageable until you add its full cost, payment schedule, and repayment conditions. Compare written terms side by side and use the same assumptions for each option. This makes it easier to see whether a structure supports the project or shifts too much risk onto you.
What Financing Terms Should You Review Before Signing?
Start with the total amount you’re expected to repay, not just the stated interest rate. Include fees, closing costs, required payments, and when each amount comes due. Then assess what the provider can claim if the project falls behind. Debt may require scheduled payments and collateral; an equity arrangement may reduce your ownership share or decision-making control instead.
- Payment obligations: Check the payment schedule, maturity date, balloon payment, and any minimum-interest provision.
- Security and recourse: Identify the property or other assets securing the funding. Confirm whether a personal guarantee or additional collateral applies.
- Flexibility and remedies: Review late-payment provisions, default remedies, early-repayment terms, and extension conditions. Get clarifications in writing before you sign.
- Ownership and control: For partnerships, document how decisions are made, how proceeds are divided, and what happens if partners disagree.
Compare payment timing with the project’s expected income. For example, a loan requiring payments before renovation is complete may create pressure even if the eventual sale or rental income appears sufficient on paper.
How Can You Stress-Test the Deal and Its Exit?
Build a conservative cash-flow view instead of relying only on the expected case. Test what happens if renovations take longer, costs rise, the property sits vacant, or sale or rental proceeds come in below plan. The goal is to see whether reserves and available cash can cover obligations during a setback, and to identify where the plan would break.
- Map payments and project expenses across the full holding period, including any balloon payment at maturity.
- State the primary repayment source, such as sale proceeds or operating income, and identify a realistic backup.
- Check that the expected sale or refinance timing matches the financing maturity and any prepayment terms.
- Don’t treat refinancing as certain. Confirm what conditions would need to be met and consider what happens if refinancing isn’t available when planned.
These checks make creative real estate funding strategies easier to compare by their actual obligations, not just their initial appeal. Ask qualified legal, tax, and financial professionals to review relevant documents and implications before committing.
How to Build a Funding Plan Around Your Real Estate Deal
A useful funding plan connects each source of capital to a specific project need and repayment path. Instead of asking only how much you can borrow, map what you need, when you need it, and how each obligation will be met. This helps you compare creative real estate funding strategies against the deal itself, not just the proposed terms.
- Define the deal. Summarize the property, purchase or project plan, timeline, and intended exit. Clarify whether you’re acquiring, renovating, holding, or combining stages.
- Quantify the full capital need. Break out purchase funds, renovation capital, closing costs, carrying costs, and reserves. Don’t assume one source will cover every category or arrive when required.
- Shortlist suitable structures. Compare options based on purpose, availability, repayment source, collateral, control, and how long you expect to need the funds.
- Verify the terms. Request written eligibility criteria, payment details, fees, maturity, collateral requirements, and default provisions. Confirm that the proposed use of funds is permitted.
- Decide after testing the plan. Check whether the combined obligations remain manageable if the project takes longer or produces less income than expected. Have qualified professionals review relevant documents and implications.
What Should an Investor Prepare Before Approaching Capital Providers?
Prepare a concise property summary, a use-of-funds breakdown, a project timeline, and clear exit assumptions. Organize relevant financial information, entity documents, and evidence of available reserves. These materials help providers assess the request and make it easier to compare responses on consistent terms. Ask each prospective provider for written eligibility requirements, fees, repayment terms, and details about collateral or guarantees.
Break the project budget into distinct needs. For example, acquisition funds may be required at closing, renovation capital may be drawn as work progresses, and reserves may need to remain available for unexpected costs or delays. Assigning each source to a specific purpose can reveal funding gaps before they affect the project timeline.
How Do You Decide Whether a Funding Mix Is Manageable?
Combining sources can help address different project stages, but it also creates more obligations and coordination. For each source, record its role in the capital stack, repayment priority, maturity date, security, and payment schedule. Then test the combined cash requirements against conservative project assumptions. Pay particular attention to overlapping maturities or repayment deadlines that depend on the same sale or refinance.
For broader capital-planning context, review this real estate funding strategy guide. If you’re evaluating capital procurement or specialized real estate investment funding, you can also discuss your real estate funding needs. Eligibility and suitability depend on the borrower, property, funding purpose, and provider criteria.
Where Koval Investments Fits in a Creative Real Estate Funding Plan
Once you’ve outlined the property, capital gap, timeline, and repayment plan, you can assess whether outside support may help clarify possible funding routes. Koval Investments provides capital procurement and real estate investment funding services. Its services may be relevant as you explore creative real estate funding strategies, but no single structure suits every deal. Suitability depends on the borrower, property, funding purpose, and provider criteria.
Preparation may also include reviewing your credit profile. Koval Investments offers credit repair and financial optimization services, including identifying and disputing credit report inaccuracies and helping clients strengthen their credit profiles. These services don’t guarantee approval or replace checking each provider’s eligibility requirements. For broader context on funding beyond real estate, see the alternative business funding overview.
What Can a Capital Procurement Conversation Clarify?
Bring the details that shape the request: the property, intended use of funds, capital gap, project timeline, and planned exit. Use the conversation to understand which options may be relevant and what remains subject to provider review. Ask practical questions before relying on a proposed structure:
- What eligibility criteria apply to this borrower, property, and funding purpose?
- Which documents should be prepared, and how will the provider assess the request?
- What are the repayment schedule, maturity, fees, collateral requirements, and default terms?
- Which assumptions or documents should qualified legal, tax, or financial professionals review?
Request written terms and verify that the proposed use of funds is permitted. Don’t treat an initial discussion as confirmation of a specific structure, rate, approval, or funding outcome.
What Is a Sensible Next Step After Comparing Your Options?
Summarize your preferred structure, why it fits the deal, and the assumptions supporting repayment and the exit. Note unresolved questions, such as whether reserves can cover a delay or whether the expected refinance is realistic. This gives you a clearer basis for discussing whether Koval Investments’ capital procurement or real estate investment funding services may fit your needs. Any potential funding remains subject to the applicable provider’s terms and criteria.
If you’re also considering a 0% interest funding solution, review the 2026 guide to 0% interest business funding. Eligibility and permitted use depend on program terms, so confirm that they align with your specific project before including this option in a funding plan.
Choose Funding That Supports the Plan Beyond Closing
The strongest creative real estate funding strategies align the property’s needs with the capital required, the repayment schedule, and a realistic exit. Compare total obligations and risk, then test whether the plan still works if costs rise, timelines shift, or expected proceeds fall short. Flexibility matters, but it can’t replace sound deal economics.
Before approaching capital providers, prepare a clear funding plan that separates acquisition, renovation, reserves, and carrying costs. Document your preferred structure and the assumptions behind repayment. Koval Investments offers capital procurement and specialized real estate investment funding, as well as credit repair and financial optimization services. Whether any funding option fits depends on the borrower, property, purpose, and provider criteria.
If you’ve defined your deal requirements and want to explore whether Koval Investments’ services may fit, discuss your real estate funding needs with Koval Investments. A well-prepared conversation can help clarify questions and next steps. Compare your options carefully and move forward with a plan that supports your investment goals.
Frequently Asked Questions
What is creative financing in real estate?
Creative financing in real estate uses deal-specific funding structures beyond a conventional investment-property mortgage. Examples include seller financing, private lending, equity partnerships, and lease options. These arrangements can differ in who provides capital, what secures it, how repayment works, or whether ownership is shared. They still involve obligations and documented terms, so review eligibility requirements, the repayment plan, collateral, and default provisions before committing.
Which creative financing strategy is best for a real estate investment?
No single strategy is best for every investment. The right fit depends on the property, project stage, capital gap, borrower, timeline, and planned exit. A renovation project with a short holding period has different needs from a rental property intended for long-term ownership. Compare total obligations, collateral, control terms, and repayment source, then test whether the deal remains viable under conservative assumptions.
Can you buy an investment property with seller financing?
Yes, you can buy an investment property with seller financing if the seller agrees to provide financing and both parties document the arrangement. The agreement should clearly state the purchase terms, payment schedule, maturity, any balloon payment, collateral, and what happens after missed payments. Review existing property obligations and have qualified professionals assess the documents and relevant implications before relying on the arrangement.
How do hard money loans differ from private real estate loans?
Hard money loans are generally short-term loans secured by real estate, often considered for acquisitions or renovation projects. Private real estate loans describe financing from a private capital provider and may have a wider range of structures and terms. The categories can overlap, so don’t rely on the label alone. Ask each provider for written details on repayment, fees, collateral, maturity, and default remedies.
Is crowdfunding a suitable way to fund a real estate investment?
Crowdfunding may suit investors who want to participate in a property investment without arranging all the capital themselves, but the structure varies by platform and offering. Review how the investment generates potential returns, how long funds may be committed, what control or ownership rights you receive, and whether resale is limited. Investor eligibility and compliance requirements also vary, so verify current terms and rules before participating.
Can you combine multiple funding sources for one property?
Yes, investors can combine sources, such as using one source for acquisition and another for renovation or reserves, if each provider permits the arrangement. Map every source’s repayment priority, maturity, collateral, and role in the capital stack. Then check whether the combined payments are manageable under conservative project assumptions. Multiple sources can fill a funding gap, but they can also add costs, coordination, and default exposure.
What risks should investors check before using creative real estate financing?
Review total repayment obligations, fees, payment timing, collateral, personal guarantees, ownership dilution, control rights, and default remedies. Creative real estate funding strategies also need an exit plan that matches the loan maturity and sale or refinance assumptions. Test the deal against delays, renovation overruns, vacancy, or lower proceeds. Don’t rely on hoped-for refinancing as the only repayment source, and have qualified professionals review relevant documents.
Can business funding be used for real estate investment?
It depends on the specific funding program and its permitted use. Don’t assume business funding, working capital, or a 0% interest funding solution can be used for every property investment. Confirm eligibility, intended use, repayment terms, and provider requirements before including a program in your plan. Koval Investments offers real estate investment funding, but suitability depends on the borrower, property, purpose, and applicable provider criteria.