Strategic Small Business Loan Consulting: A Guide to Capital Procurement in 2026
Most entrepreneurs believe a lender's rejection is a final judgment on their company's potential, but it's often just a reflection of an unoptimized financial profile. You've likely felt the frustration of a low credit score blocking an SBA approval or the confusion of trying to pick the right loan type while your growth stalls. It's difficult to find the time for endless applications when you're busy running a business. We understand that the search for capital shouldn't feel like a gamble against the house. You deserve a steady hand to guide you through these complex financial landscapes.
This guide explains how professional small business loan consulting transforms your eligibility from the ground up. You'll discover how to engineer a profile that commands 0% interest funding and high-limit SBA capital. By focusing on strategic credit restoration and intentional planning, you can move past the stress of high rates and limited options. We're going to walk through a clear roadmap for business expansion, showing you how to secure the working capital you need for a successful 2026. It's time to stop chasing lenders and start positioning your business as their most attractive investment.
Key Takeaways
- Understand why viewing capital procurement as a strategic partnership, rather than just a transaction, is the key to long-term business scalability.
- Learn how professional small business loan consulting utilizes credit restoration to optimize your financial profile and unlock significantly higher funding limits.
- Discover the specific advantages of 0% interest funding solutions and how they complement SBA-backed capital for equipment or real estate needs.
- Identify the critical steps of the procurement roadmap, starting with a professional business valuation to ensure your capital requests align with your actual growth stage.
- Explore how a success-based consulting model minimizes your financial risk while positioning your brand for confident national expansion.
Beyond the Application: Why Small Business Loan Consulting is a Strategic Necessity
Procuring capital involves much more than just submitting a digital application and waiting for a response. For many owners, the process feels like a black box where inputs lead to unpredictable rejections or, worse, unfavorable terms. This is where small business loan consulting becomes a strategic necessity. Rather than treating capital as a one-time transaction, a consultant views your financial structure as a holistic ecosystem that requires optimization before any request is made to a lender.
Many entrepreneurs fall into the trap of "shotgunning" applications. They apply to every online lender they find, hoping something sticks. This approach often results in multiple hard credit inquiries, which can lower scores and signal desperation to underwriters. A strategic consultant protects your profile by identifying the right fit before a single inquiry occurs. They also uncover hidden opportunities, such as 0% interest business funding solutions, that traditional banks rarely mention to their clients.
Effective consulting is about engineering eligibility from the ground up. It shifts the focus from "finding a lender" to "becoming an irresistible borrower." By auditing your current financial standing and repairing credit inaccuracies early, a consultant ensures you approach the market from a position of strength. This proactive stance allows you to secure higher limits and better terms that would otherwise be out of reach.
The Difference Between a Lender and a Strategic Consultant
A direct lender is essentially a salesperson for a specific financial product. Their goal is to move their own inventory, regardless of whether it's the most efficient choice for your growth. Small business loan consulting flips this dynamic. A consultant acts as your advocate, scanning the entire market to find the best alignment for your goals. This objective stance helps you avoid high-interest cycles and predatory lending traps. By utilizing a success-based partnership model, the consultant's interests align perfectly with yours; they only win when you secure the capital you need.
Navigating the 2026 Funding Landscape
The financial environment in 2026 has seen a marked shift in how institutions evaluate risk. Traditional banks have tightened their credit standards significantly, leading to higher rejection rates for even established firms. This volatility makes the role of the U.S. Small Business Administration even more critical, as their guarantee programs provide a safety net for lenders. However, accessing these programs requires a level of financial preparation that most owners don't have the time to manage. Alternative capital procurement is the new standard for businesses that want to scale without the constraints of institutional rigidness.
Engineering Eligibility: The Critical Role of Credit Restoration
While many lenders provide a "yes" or "no" based on your current score, effective small business loan consulting focuses on the mechanics behind that number. Credit restoration isn't just about fixing mistakes. It's the bedrock of successful capital procurement. A higher score directly translates to lower risk in the eyes of an underwriter. This shift in perception unlocks lower interest rates and more flexible repayment terms that can save your business thousands over the life of a loan.
Strategic small business loan consulting helps identify common report inaccuracies, which often include duplicate accounts, incorrectly reported late payments, or outdated balance information. These errors act as invisible barriers to funding. Disputing these effectively requires a methodical approach to ensure they're permanently removed rather than just temporarily suppressed. By cleaning up these discrepancies, you increase your funding limits and present a more stable image to potential capital partners.
Building a Stronger Financial Profile
Professional business credit repair services are essential because personal and business credit are deeply intertwined. For most small business owners, personal credit remains the primary indicator of financial responsibility during the underwriting process. Optimizing your debt-to-income ratio and ensuring your profile is lean and accurate allows you to command higher capital limits. If you're ready to see how your profile stacks up, exploring strategic credit repair can be your first step toward total financial optimization.
Fixing Credit for SBA Loan Approval
The SBA loan programs and eligibility guidelines set specific benchmarks that are difficult to meet without preparation. For SBA 7(a) and 504 programs, lenders typically look for a FICO SBSS score of at least 155, though many preferred lenders require 160 or higher for competitive terms. Addressing historical defaults or high credit utilization before you apply is mandatory. We define the credit optimization window for SBA readiness as the 90 to 120 day period where a business intentionally cleanses its profile to ensure maximum approval odds. This window allows for the removal of negative items and the seasoning of new, positive tradelines, making your application significantly more robust.
Strategic Capital Selection: 0% Interest Funding vs. SBA Loan Assistance
Selection is the stage where strategy meets math. Once your profile is optimized, the goal shifts to minimizing the cost of capital while maximizing your growth runway. Expert small business loan consulting ensures you don't just take the first offer; you take the one that aligns with your expansion timeline. Not all capital serves the same purpose, and choosing the wrong structure can lead to cash flow bottlenecks that hinder rather than help your progress.
The 0% Interest Funding Solution
Unsecured working capital is often the fastest path to scaling without the burden of immediate interest. By accessing 0% interest business funding, you can avoid the compounding debt that often stalls young companies. This strategy involves stacking multiple business credit lines to create a pool of zero-interest capital. It's a precise process that requires a specific sequence of applications to prevent inquiry drag on your credit report. This type of funding is ideal for inventory spikes, marketing campaigns, or short-term operational gaps. It allows you to use the bank's money to generate revenue before a single dollar of interest is ever charged.
Comprehensive SBA Loan Assistance
For larger, long-term investments like commercial real estate or heavy machinery, SBA loan assistance provides a more permanent structure. The SBA 7(a) program remains the most versatile option for general working capital, often offering maturity terms up to 10 years, while real estate loans can extend to 25 years. In contrast, the 504 loan program is specifically designed for fixed assets, providing long-term, fixed-rate financing that protects you from market volatility. A consultant streamlines the extensive documentation process, ensuring your cash flow projections and business plan meet the rigorous standards of 2026 lenders. This support is vital because even minor clerical errors can lead to months of delays.
Analyzing the true cost of capital is essential for long-term health. While unsecured lines offer speed and no collateral requirements, they usually have introductory periods that require a clear exit strategy. SBA loans offer lower rates over much longer terms but require more extensive vetting and often involve collateral. This vetting process relies heavily on the credit integrity discussed in previous sections. Following FTC guidance on credit restoration ensures that the foundation of your application is legitimate and verifiable. Choosing between these options isn't about finding the "cheapest" money; it's about finding the capital that provides the highest return on investment for your specific stage of expansion.
The Consulting Roadmap: From Business Valuation to Successful Procurement
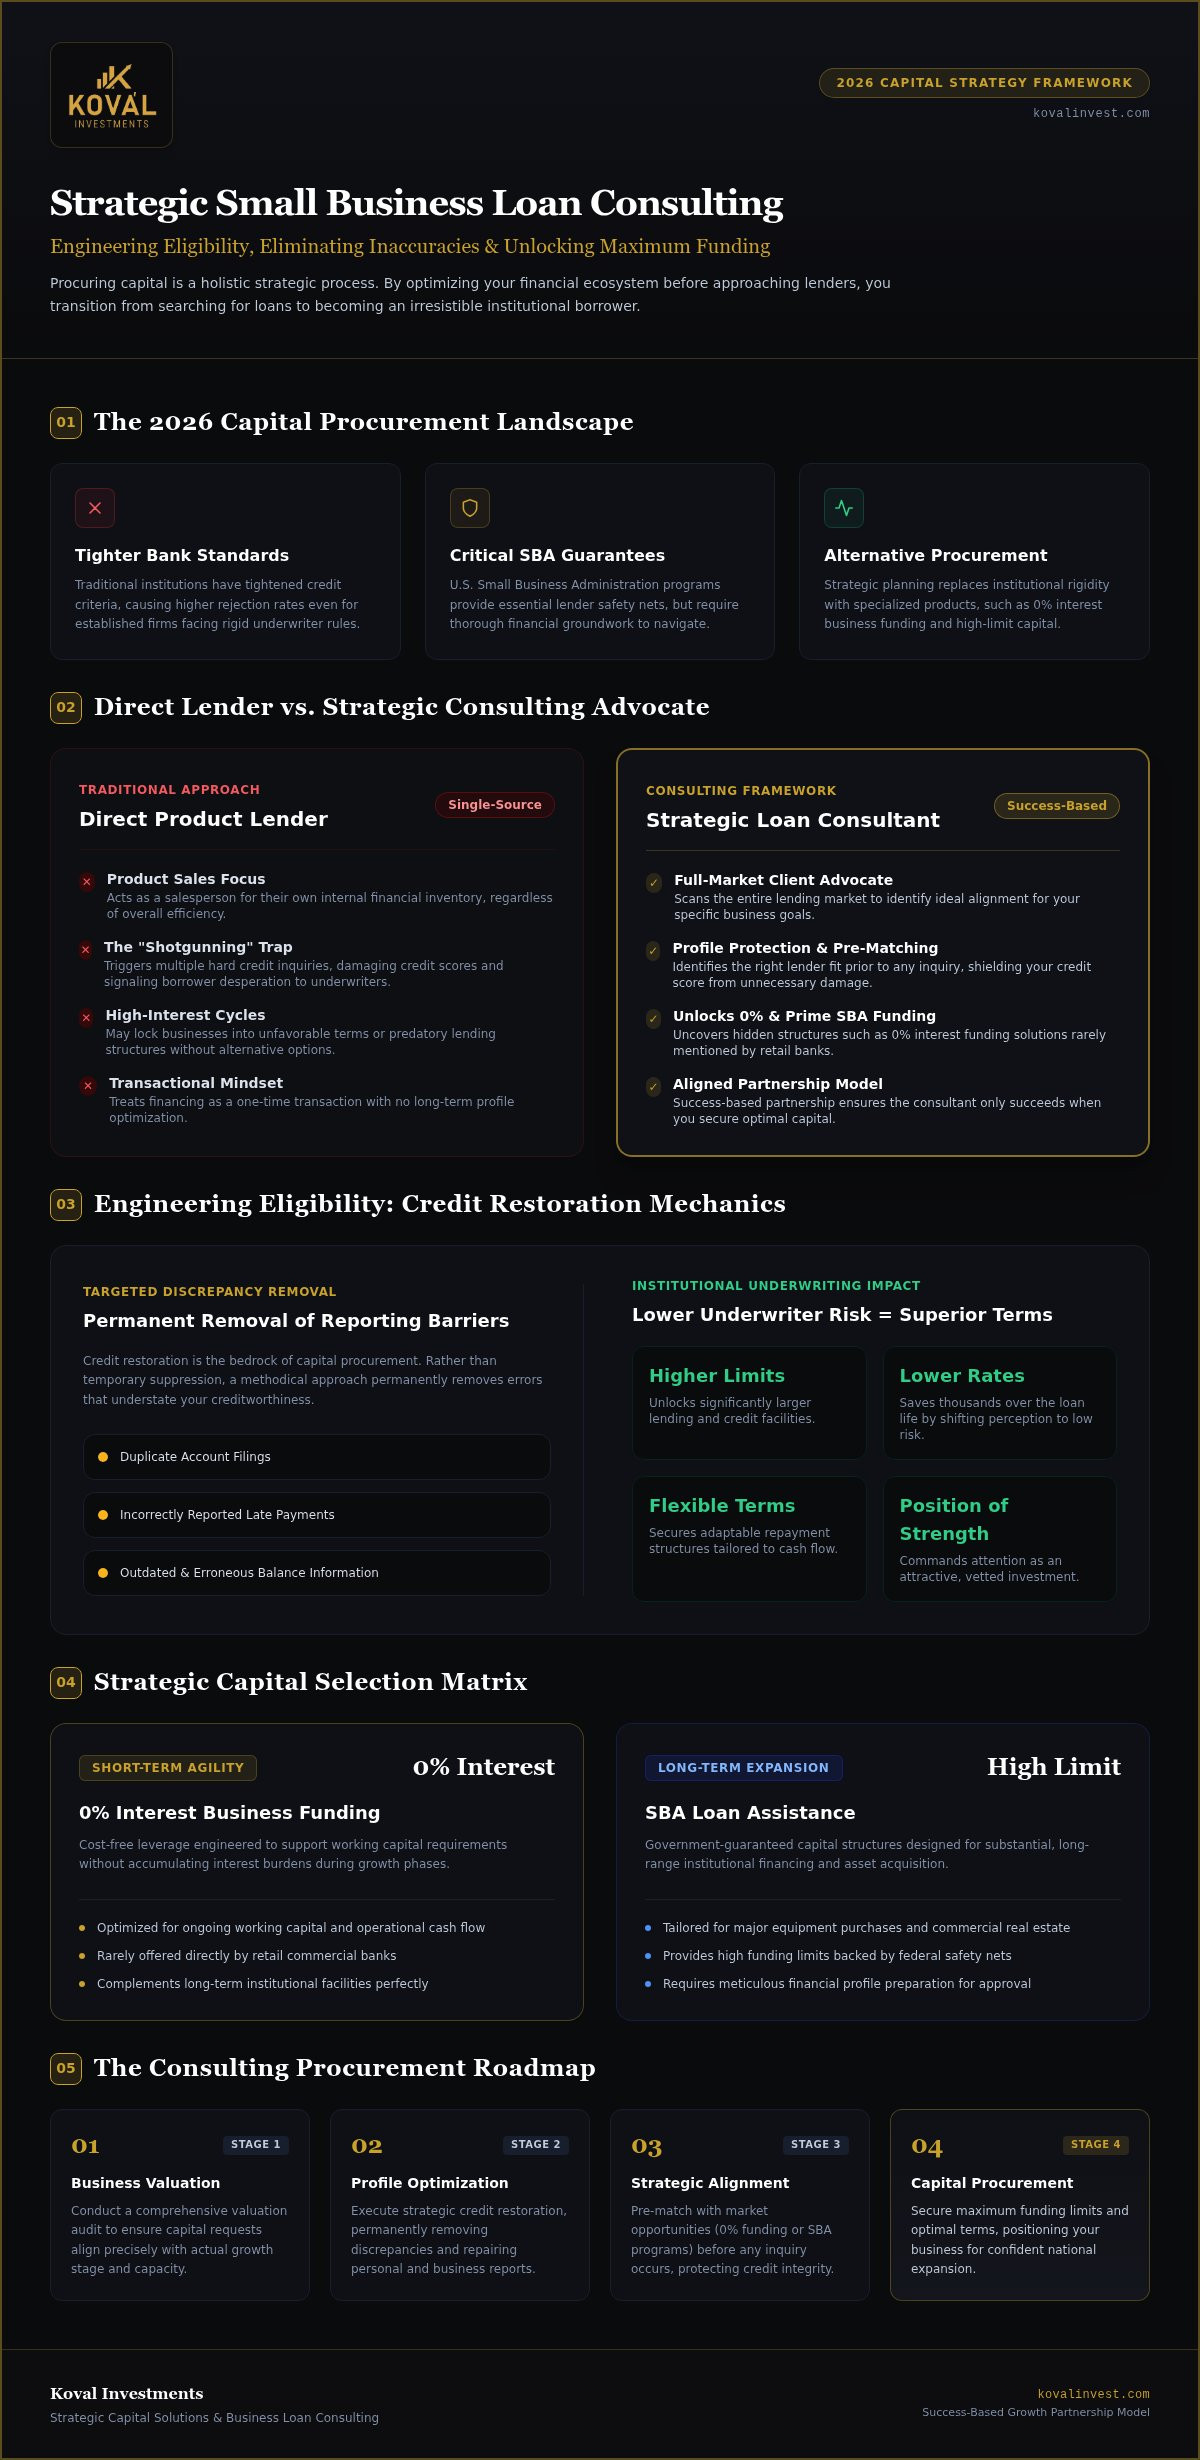
Successful capital procurement follows a methodical path that begins long before a lender sees your name. While many direct lenders promise a three-step "Apply, Approve, Fund" process, this speed often comes at the cost of lower limits and higher interest rates. Professional small business loan consulting replaces this rush with a four-step roadmap designed to maximize your leverage. We start by establishing exactly what your business is worth and what it can realistically support. This data-driven approach removes the guesswork from the application process and ensures you don't leave capital on the table.
Why Business Valuations Matter for Funding
A professional business valuation is the first pillar of the roadmap. Underwriters use these metrics to justify higher loan amounts, especially when you are using working capital for business acquisition. In the context of mergers and acquisitions consulting, an accurate valuation ensures you aren't overpaying for a competitor or selling yourself short. It transforms your request from a "wish" into a data-backed proposal that lenders can easily approve. This level of transparency builds immediate trust with financial institutions and positions you as a sophisticated borrower rather than a high-risk applicant.
The second step involves a comprehensive financial audit and credit restoration. We've already established that credit is the foundation of capital procurement. Here, we apply that clean profile to your specific funding goals. Step three moves into strategic planning. Strategic small business loan consulting ensures that every dollar you secure aligns with your long-term expansion rather than just solving a temporary cash flow issue. It's about looking two or three years ahead to ensure your debt service doesn't outpace your projected revenue growth.
Strategic Planning for Capital Deployment
Deployment is just as important as procurement. Strategic planning defines how every dollar will generate a return on investment. This foresight prevents you from becoming over-leveraged, which is a common risk when businesses scale too quickly. We also consult on exit strategies and M&A transitions, ensuring that the debt structure you build today doesn't hinder a potential sale tomorrow. It's about building a legacy, not just a balance sheet. The final step of our roadmap is multi-lender submission and negotiation. By presenting your optimized profile to several institutions simultaneously, we secure the most competitive terms available in the 2026 market. If you're ready to begin this journey with a partner who values your success, you can schedule a strategic valuation to determine your true funding potential.
Scaling with Confidence: How Koval Investments Facilitates National Expansion
Koval Investments operates on a fundamental belief: your success is our success. Since our founding in 2018, we've positioned ourselves as a steady hand in complex financial landscapes. Many firms act as distant service providers, but we function as an "insider" strategic partner. Our success-based philosophy removes the traditional financial risk from the client, framing our engagement as a collaborative venture. When you partner with us, you're gaining access to deep industry expertise that bridges the gap between high-level financial strategy and your day-to-day operational realities. We believe in building a legacy, not just a balance sheet.
Our approach to small business loan consulting is specifically designed for the ambitious founder. Whether you're seeking real estate investment funding or working capital for a national rollout, we provide the precision and stability required to navigate 2026's tightening credit standards. We don't rely on the cold, detached algorithms used by large institutional banks. Instead, we offer a personalized connection that respects your unique operational constraints and expansion goals. By choosing professional small business loan consulting with a firm that understands the national landscape, you ensure your business is positioned for long-term scalability.
A Boutique Approach to National Funding
Large financial institutions often treat small business owners as data points on a spreadsheet. We reject this impersonal model in favor of a boutique approach that prioritizes the quality of the relationship. Our commitment to "straight-talk" advisory means you'll always have a clear understanding of your standing and your options. We support long-term corporate development by looking beyond your first loan. Our team functions as a mentor equally invested in your success. This pragmatic mentality ensures that we only move forward when there is a clear, win-win path for your company's advancement. This transparency ensures that you feel informed and empowered throughout the procurement process.
Next Steps: Securing Your Business Capital
Moving from strategy to execution requires organization and intent. To prepare for a review with our consultants, you should gather your most recent business tax returns, profit and loss statements, and current debt schedules. In your initial strategic planning session, we'll dive deep into your business valuation and credit profile to identify the most efficient path to capital. We'll outline a specific sequence of actions to optimize your eligibility for 0% interest lines or SBA-backed funding. It's time to stop navigating these challenges alone. You can schedule your capital procurement consultation with Koval Investments today to begin engineering your financial future.
Engineering Your Financial Future in 2026
Capital procurement in 2026 requires a shift from reactive searching to proactive engineering. We've explored how professional small business loan consulting transforms your eligibility through methodical credit restoration and precise business valuations. By aligning your capital needs with the right instruments, whether that's 0% interest funding or long-term SBA capital, you protect your cash flow and ensure sustainable growth. You don't have to navigate these tightening credit markets alone or settle for predatory rates that hinder your progress.
It's about moving forward with a partner who values your long-term success over a quick transaction. Koval Investments offers a success-based consulting model that minimizes your risk while maximizing your procurement limits. Our expertise in comprehensive financial optimization and specialized funding solutions ensures you aren't just getting a loan; you're building a strategic foundation for national expansion. The roadmap to high-limit capital is clear when you have the right advisor by your side. Partner with Koval Investments for Strategic Capital Procurement to start your optimization journey today. We're ready to help you scale with confidence.
Frequently Asked Questions
What is the difference between a loan broker and a small business loan consultant?
A loan broker typically acts as a middleman focused on a single transaction and a commission from a specific lender. In contrast, small business loan consulting involves a strategic partnership where the advisor optimizes your entire financial profile before approaching the market. We focus on long term corporate development and engineering your eligibility for the best possible terms. This holistic approach ensures you aren't just getting a loan but are building a sustainable capital structure.
How long does the business credit repair process take for loan eligibility?
The business credit repair process generally requires a dedicated window of 90 to 120 days to achieve maximum results. During this time, we identify and dispute inaccuracies while allowing new positive tradelines to season. This timeframe is essential for meeting the rigorous underwriting standards of 2026 lenders. Rushing the process often leads to temporary fixes rather than the permanent profile optimization needed to secure high limit funding at the lowest possible interest rates.
Can I really get 0% interest business funding in 2026?
Yes, 0% interest business funding remains a highly effective growth tool in 2026 through the strategic stacking of business credit lines. This method allows entrepreneurs to access unsecured working capital without the burden of immediate interest payments during the introductory period. It requires a specific sequence of applications to protect your credit score from excessive inquiry drag. Our consultants guide you through this process to ensure you maximize your zero interest runway for inventory or marketing.
Do I need a business valuation before applying for an SBA loan?
A professional business valuation is highly recommended before applying for an SBA loan to justify your requested capital amount. Underwriters look for data backed evidence that your company's value and cash flow can support the debt service. This is especially critical when using working capital for business acquisition or mergers. Having a valuation in hand transforms your application into a sophisticated proposal, making it much easier for lenders to approve higher limits with confidence.
What are the minimum credit score requirements for SBA loan assistance?
Most lenders providing SBA loan assistance look for a minimum FICO SBSS score of 155, though 160 is often the benchmark for competitive terms. Personal credit scores also play a vital role, as they indicate your historical financial responsibility to the bank. We focus on reaching these benchmarks through targeted credit restoration before you submit an application. Meeting these specific requirements is the first step in unlocking the long term benefits of SBA 7(a) or 504 programs.
How much does small business loan consulting typically cost?
Small business loan consulting at Koval Investments operates on a success based model designed to align our interests with your growth. We charge professional fees for specific deliverables like business valuations and credit restoration services, but our primary focus is on the win-win outcome of your procurement. This structure minimizes your financial risk as a client. By investing in professional guidance, you avoid the much higher costs of predatory lending or the missed opportunities of a bank rejection.
Can a consultant help if I have been rejected by my local bank?
We can certainly help if a local bank has rejected your application. Rejections often happen because the bank's rigid algorithms don't account for your full potential or because your credit profile contains fixable errors. Our consultants perform a deep audit to find the specific reason for the denial. We then restructure your financial narrative and repair your credit to present a much stronger case to a broader network of national lenders who understand your industry better.
What industries do Koval Investments specialized funding solutions cover?
Our specialized funding solutions cover a wide range of industries across the United States, including real estate investment, professional services, and retail. We work with business founders and corporate leaders who need strategic capital for acquisition, equipment, or national expansion. Because our approach is boutique and personalized, we adapt our procurement strategies to the specific operational constraints of your sector. Our national reach ensures that your specific industry doesn't limit your access to high quality capital sources.